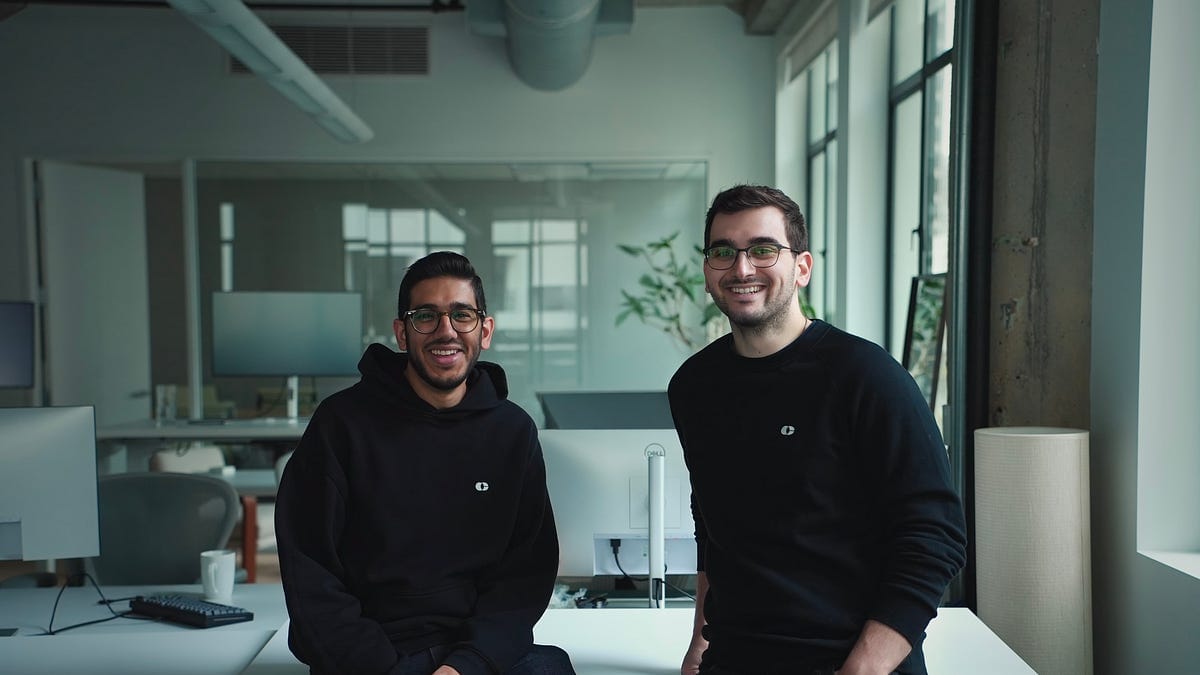
For founders, raising venture capital and selling a company can feel like two entirely different challenges. One is about convincing investors to believe in what you are building. The other is about finding a buyer who sees enough value in that business to acquire it.
But Andrei Serban, founder of Console, discovered that the two processes have more in common than most entrepreneurs realize.
Serban previously founded Fuzzbuzz, an application security testing company that raised a $3.5 million seed round, went through Y Combinator, and was eventually acquired by Rippling. After spending a few months working at Rippling, he left to start Console, a company rethinking how businesses manage internal IT and back-office operations using AI agents.
Console subsequently raised $39 million from investors including Thrive Capital, SV Angel, and DST Global. Its fundraising journey offers lessons on preparing for investor conversations, creating a compelling market narrative, choosing the right investors, and running a focused fundraising process.
In an episode of How I Raised It, produced by FounderSuite and Fundingstack, Serban also shared what he learned from selling his first company and why founders should approach acquisition negotiations with more preparation and a clearer sense of their options.
Here are the lessons founders can take from his experience.
1. Treat Selling Your Company Like a Fundraise
An acquisition can arrive at an unexpected moment. A larger company may express interest, conversations can become serious quickly, and founders who have spent years pushing their business forward may suddenly find themselves considering an offer.
That was broadly the experience at Fuzzbuzz. The company was gaining traction selling security software to large enterprises and US government customers. As Serban sensed a shift in the market, an acquisition by Rippling began to make sense. The opportunity offered a path for the team to continue building within a larger company.
Looking back, Serban believes the team could have approached the sale more deliberately.
“Selling a company is actually quite similar to raising,” he explained.
In a fundraising process, founders identify potential investors, prepare materials, communicate their story, and manage conversations toward a decision. Serban believes an acquisition process deserves the same structure.
If you are actively exploring a sale, start by identifying a list of companies that could be suitable acquirers. Prepare the necessary materials in advance, understand what you want from a transaction, and establish a process for managing conversations. If a company approaches you first, be ready to move quickly rather than improvising once the opportunity appears.
Without that preparation, an acquisition discussion can drag on for months. Founders may find themselves spending significant time with a large company whose interest feels validating after years of difficult work. Yet that attention does not guarantee a transaction.
Serban emphasized the importance of defining what the process is supposed to achieve and when it should begin and end. A prolonged sale process can distract the team from running the business, particularly if the acquisition never closes.
He also acknowledged that, in hindsight, Fuzzbuzz probably should have hired a banker or advisor to help manage the process.
The lesson is not that every startup needs an advisor to sell its business. It is that founders should recognize an acquisition as a significant business process in its own right, one that benefits from preparation, clear objectives, and experienced support when appropriate.
Understand what you can negotiate
Another important lesson concerns the terms of an acquisition.
Founders may assume that a large company has a standard process and that the terms presented to them are largely fixed. Serban's experience suggests a different approach.
“There are many more things you can negotiate than I think founders may think, especially in the moment,” he said.
The purchase price is only one part of a deal. Depending on the transaction, founders may also need to consider earn-outs, cash and equity components, and how long they are expected to remain with the acquiring company. Serban noted that earn-outs can run for two years or, in some cases, four years.
These terms can materially affect the outcome for a founder, so it is worth understanding the complete package rather than focusing exclusively on the headline acquisition price.
Leverage matters, and every transaction has its own circumstances. But Serban's advice is to start negotiations with an open mind instead of assuming the buyer's initial proposal defines the limits of what is possible.
2. Know When the Next Opportunity Is Worth More Than the Current One
Selling Fuzzbuzz gave Serban another decision to make: what should he do next?
He joined Rippling in early 2023, where he worked as the product lead for its IT product. During that period, he became increasingly interested in how IT and back-office operations could be redesigned.
The timing mattered. ChatGPT had launched only a few months earlier, and Serban saw the potential for AI to change how companies handled internal requests and operational workflows.
Traditional IT support often requires employees to submit tickets, wait for someone to review them, and then coordinate with another person to resolve the issue. As companies adopt more software and begin deploying AI agents, Serban believed these processes could become even more difficult to manage.
He saw an opportunity to build a system in which AI agents could handle routine requests, follow company policies, and interact with internal tools, allowing IT and other teams to focus on higher-value work.
That opportunity was compelling enough for him to leave Rippling after roughly three to four months and start Console, even though doing so meant giving up part of the financial package tied to his previous exit.
When Nathan Beckord asked about that trade-off, Serban confirmed that the decision involved choosing between remaining at Rippling to complete his earn-out and pursuing the opportunity he saw in Console.
He has no regrets about that choice.
For founders who have sold a company, the experience highlights an important consideration: the most financially comfortable next step is not necessarily the most valuable one over the long term.
That does not mean founders should casually abandon an earn-out or walk away from guaranteed compensation. The decision depends on the contractual terms, financial circumstances, and strength of the opportunity ahead. But it is worth evaluating the cost of waiting, especially when a new market or technological shift creates a time-sensitive opening.
Serban's decision was grounded in a specific thesis about how AI could reshape company operations. He had been speaking with IT leaders, had seen the limitations of existing workflows firsthand, and believed the problem would become more pressing as AI agents spread through organizations.
That conviction helped him make a consequential decision before the opportunity passed.
3. Build Your Fundraising Story Around the Market, Not Just Your Product
One of the most useful lessons from Console's fundraising journey is that investors need to understand why a business should exist before they can fully evaluate why a particular startup will succeed.
When Console was raising capital, IT service management and back-office automation were not necessarily obvious areas of excitement for venture investors. Serban realized that the company had to do more than describe its product. It needed to explain why the market itself mattered.
“When you're fundraising in a space that isn't obvious, you're actually selling investors on two things,” he said. “The first one is the market.”
Only after investors understand why a market deserves attention can founders make a convincing case for why their company is positioned to win it.
Console approached this challenge by preparing a two-page memo that explained why the market was important, how the team believed it would develop over the next five years, and what Console was building in response.
The memo was deliberately high-level. It did not rely on a collection of statistics to make its case. Instead, it laid out the company's perspective and gave investors a framework for understanding the opportunity before their first meeting.
The team had initially written a much longer version, around ten pages, before condensing it into something investors could absorb quickly.
This is a useful approach for founders building in emerging or misunderstood categories. A pitch deck may explain the product, traction, team, and business model, but it can struggle to communicate a broader market shift in the limited time available during a meeting.
A concise market narrative gives investors a reason to care about the problem before the conversation turns to the company.
It can also improve how founders communicate outside fundraising. A clear explanation of the market can inform customer conversations, hiring, sales, and marketing. If the story is difficult to explain to an investor, it may also be difficult to communicate to prospective customers or employees.
Use fundraising to step back from the business
Serban sees fundraising as an opportunity to reassess the company, rather than simply a distraction from building it.
Founders can spend months deep in product decisions, customer requests, hiring, and day-to-day execution. That work is necessary, but it can make it difficult to step back and ask whether the company is still moving in the right direction.
Preparing to raise forces founders to answer fundamental questions: What market are we pursuing? Why does the problem matter now? What changes over the next few years could make this opportunity much larger? What evidence suggests we can build a successful business here?
As Serban explained, fundraising gives founders a chance to “zoom out” and look at the broader direction of the company.
The resulting narrative should not be limited to investor meetings. It can become the foundation for how the company presents itself to the market.
4. Run a Focused Fundraise Instead of Letting It Consume Your Calendar
Console raised its Series A in a highly concentrated process.
Serban said the company had spent time building relationships with investors who had already expressed interest. When it was ready to raise, the team consolidated those conversations into a short window rather than meeting investors sporadically over several months.
The company spoke with approximately 30 funds during the first week. Serban cleared his schedule to focus on those meetings, then sent follow-up materials and held second and third meetings during the following week. By the end of that second week, the team had received term sheets and had a clear idea of which investors it wanted to work with. The remaining time was spent closing the round.
The team had prepared its materials in advance, including the two-page market memo, so it could use meetings to have more productive conversations instead of repeatedly explaining the opportunity from scratch.
Serban framed the choice simply: would he rather spend two months fundraising or spend two weeks focused almost entirely on it?
Either way, the process would take attention away from the business. Consolidating the meetings helped reduce that distraction.
This approach offers a practical lesson for founders preparing to raise. A fundraising process does not have to become an ongoing series of loosely coordinated conversations. With preparation, a clear investor list, and a defined timeline, founders can create a process that helps investors evaluate the opportunity in a comparable window.
That does not mean every round can be completed in two weeks. The timeline depends on the business, market, investor appetite, and stage of the company. Nor should founders rush into a deal simply to meet an arbitrary deadline.
The principle is to be intentional about the process.
Before beginning, founders should know how much they intend to raise, which investors they want to meet, what materials they need, and how they will follow up. They should also be prepared to adjust the plan when circumstances change.
Serban's own process illustrates why that flexibility matters. DST Global was not on the initial list of approximately 30 investors. The firm came into the process later through an introduction from SV Angel. After speaking with the team, Serban became interested and adjusted the plan to move the conversation forward.
Preparation gave the company structure. Adaptability allowed it to take advantage of an unexpected opportunity.
Use the right materials for the right conversation
Console's market memo also served a practical purpose: it made the first meeting more productive.
A short investor meeting offers limited time to explain a complex business, establish context, and answer questions. By sending the memo beforehand, Console gave investors a chance to think about the market and conduct some of their own research before speaking with the founders.
The goal was not to overwhelm investors with information. It was to make sure they arrived with a better understanding of the opportunity.
For founders, this is a reminder to think about the fundraising experience from the investor's perspective. What does an investor need to understand before a meeting? What information can be shared in advance? Which questions deserve live discussion rather than another slide?
A thoughtful pre-meeting memo, a well-organized data room, and clear follow-up materials can help reduce friction throughout the process. The materials should support the conversation, not replace the founder's ability to explain the business.
5. Choose Investors for the Relationship, Not Just the Brand
When founders receive multiple term sheets, it can be tempting to prioritize the most recognizable venture capital firm. A prestigious investor can bring credibility, attract attention, and make a fundraising announcement more visible.
But Serban believes founders should place greater weight on the individual partner they will work with.
“The thing that we always optimize for is the best partner,” he said, explaining that founders should consider what their working relationship with that person might look like over the next decade.
For Console, the choice was about more than a firm's reputation. Serban valued investors who could think deeply about the business, understand the underlying problem, and help the company make better decisions.
That distinction becomes especially important after a round closes. The announcement may generate attention for a day, but the relationship with the investor can continue through board meetings, strategic decisions, future fundraising, difficult periods, and major company milestones.
Founders should therefore evaluate the person who will actually work with them. How do they think through problems? Do they understand the market? Can they offer useful perspectives when the business faces a difficult decision? Do their communication styles and expectations fit the founding team's approach?
Serban also offered practical advice for identifying the right partner within a larger firm.
Existing investors can be useful sources of introductions and guidance because they often know other investors across the industry. Founders can also research a firm's team and past investments to identify partners whose interests and expertise align with their business.
A founder building B2B software, for example, should focus on investors with relevant experience rather than approaching a partner whose primary focus is an unrelated sector.
The objective is not simply to get a meeting with a prominent firm. It is to find the person most likely to understand the business and contribute to its long-term success.
6. Build the Company First. Fundraising Should Support the Mission.
Serban's final advice brings the other lessons together: founders should treat fundraising as part of building a company, rather than as the company's central objective.
He believes founders should raise when the timing makes sense for the business, rather than forcing a process simply because fundraising has become the next milestone on a plan.
Investors can usually tell when a founder is pushing a round without a convincing reason. A more compelling approach is to demonstrate a clear mission, explain what the company is trying to accomplish, and show how additional capital will help it get there.
“I'm on this mission and you either are helping me get there or you're not,” Serban said, describing the mindset he believes founders should bring into fundraising.
That perspective changes the conversation. Instead of treating every investor meeting as a request for approval, founders can use the process to determine which investors understand the opportunity and are genuinely suited to support it.
It also gives founders permission to be selective. A term sheet is important, but the right partner, the quality of the relationship, and the capital required to execute the business plan matter too.
At the same time, Serban cautions against becoming too attached to a fundraising plan. Console's experience with DST Global showed that an unexpected investor can be worth making room for, even when the conversation does not fit the original schedule.
A good process provides direction without preventing founders from responding to new information.
The Takeaway for Founders
Andrei Serban's journey from Fuzzbuzz to Console offers a set of practical lessons for founders at different stages of the startup lifecycle.
If you are considering an acquisition, prepare for it with the same discipline you would bring to a fundraise. Define your goals, organize your materials, keep the process moving, and understand that deal terms extend beyond the purchase price.
If you are raising capital, build a clear narrative around the market and why the opportunity matters. Prepare investors before meetings, consolidate conversations where possible, and choose partners based on the value of the relationship rather than the firm's name alone.
Most importantly, keep the business at the center of every decision. Fundraising can be a useful opportunity to reassess your strategy, sharpen your story, and determine what the company needs next. But capital is a means of building the business, not the end goal.
As founders prepare for their next round, tools such as Foundersuite can help organize investor research, manage outreach, and keep fundraising activity structured. That leaves more room for the work that ultimately makes a company worth investing in: understanding the market, building a product that customers value, and executing on a clear vision.
An Update: Console’s Acquisition by Palo Alto Networks
Since this conversation, Andrei Serban’s journey has reached another major milestone. On September 1, 2026, Palo Alto Networks acquired Console in a deal reportedly valued at $500 million in cash and stock. Serban now serves as a vice president at Palo Alto Networks.
The acquisition brings his story full circle. After building Fuzzbuzz, raising venture capital, and navigating its sale to Rippling, Serban went on to identify another opportunity in enterprise technology and build Console around it.
For founders, the outcome reinforces several of the lessons he shared in this conversation: recognize important shifts in the market, prepare carefully for major transactions, and stay focused on building a business that solves a meaningful problem. His experience also illustrates that selling a company can be a transition to a new chapter, rather than the end of a founder’s journey.